Space Semiconductor Market Overview Analysis By Fortune Business Insights Analysis
Market Size & Growth Outlook
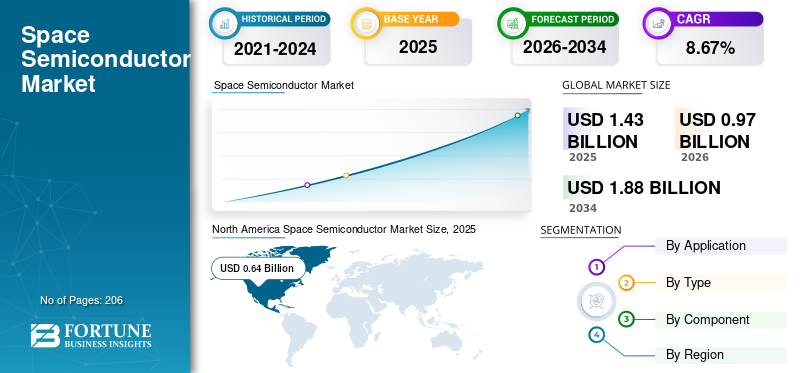
According to Fortune Business Insights: The global space semiconductor market was valued at USD 1.43 billion in 2025 and is projected to grow from USD 0.97 billion in 2026 to USD 1.88 billion by 2034, exhibiting a CAGR of 8.67% during the forecast period. North America dominated the market with a 44.06% share in 2025.
Space semiconductors are electronic components specifically designed, manufactured, and qualified to operate reliably in the harsh and demanding environment of space — including extreme temperatures, radiation, vacuum, and microgravity. Silicon and alternatives including Gallium Arsenide (GaAs) are primary semiconductor materials, while Silicon Carbide (SiC) is valued for its thermal and electrical properties. Space semiconductors are typically used in satellites, spacecraft, and space electronics applications and are considerably more expensive than regular semiconductors, though far more reliable for extreme-environment operation. The growing constellation of satellites is expected to drive satellite manufacturing, propelling market growth. The COVID-19 pandemic adversely impacted component delivery timelines and manufacturing, with the Semiconductor Industry Association reporting broad global chip supply challenges that hampered R&D activities dependent on physical laboratory presence and collaborative efforts.
Get a Sample Research PDF: https://www.fortunebusinessinsights.com/enquiry/request-sample-pdf/105223
Market Trends
Use of System-on-Chip (SoC), AI, and ML Algorithms: A system-on-chip combines high-level functional elements of an electronic device onto a single chip rather than using separate motherboard-mounted components — incorporating functions including CPU, GPU, modem, and signal processing into a unified microchip. In October 2023, Coherent Logix Inc. launched HyperX: Midnight, a fourth-generation HyperX SoC for space and defense industries delivering up to 4x more computing throughput at half the power and 40% lower price than leading radiation-hardened FPGAs — a powerful, low SWaP (size, weight, power) combination critical for Space 2.0 companies, enabling greater capacity within smaller satellite bus sizes and significantly reducing launch costs. Quantum technology, AI and ML algorithms, public-private partnerships, product innovations, and government initiatives are additional key market trends.
Market Growth Factors
Surge in Satellite Constellations: The primary growth driver is the surge in satellite constellation deployment serving Earth observation, communication, and navigation purposes, necessitating advanced electronics for consistent and reliable operation in the challenging space environment. According to the U.S. Government Accountability Office, active satellite counts rose from 1,400 in 2015 to 5,500 by spring 2022, with the GAO projecting 58,000 new satellites to be launched by the end of the decade — more than doubling the current number of operational spacecraft and directly propelling space semiconductor demand.
Technological Advancements in Manufacturing and Processing Techniques: Major players are focused on developing technologically advanced semiconductors capable of sustaining space environment conditions while improving reliability and efficiency. Gallium oxide exhibits the capacity to support high currents and voltages with minimal energy losses and can be turned into high-quality films using cost-effective techniques — offering manifold advantages over silicon for challenging environments including space exploration due to its ability to endure high temperatures and radiation without significant degradation. In August 2023, researchers at KAUST (King Abdullah University of Science and Technology) developed the world's first flash memory device using gallium oxide, demonstrating superior resilience to extreme temperatures compared to traditional electronics.
Restraining Factors
Supply Chain Disruptions and Geopolitical Tensions: Supply chain disruptions stemming from raw material shortages, transportation issues, and geopolitical instabilities pose significant threats to smooth space semiconductor market operation, resulting in delays, increased costs, and hampered production efficiency. In September 2022, Philippine Long Distance Telephone Company (PLDT Inc.) reported that delayed delivery of essential chips represents a major challenge for LEO satellite manufacturers, with persistent semiconductor shortages potentially impacting satellite producers critical to telecommunications services. Geopolitical tensions further compound sector challenges, with strained international relations and trade conflicts leading to restrictions on the movement of critical components and technologies — hindering innovation pace while raising concerns about component reliability and accessibility for space applications.
Segmentation Analysis
By Application: The satellite segment dominated the global market with a 79.13% share in 2026, estimated to grow significantly due to growing demand for satellite communication and navigation services. Semiconductors designed for artificial satellites orbiting Earth are crucial for satellite communication, earth observation, navigation, and scientific research. The launch vehicle segment is estimated to be the fastest-growing segment, driven by increasing demand for advanced and compact semiconductors used in rocket and space shuttle electronic systems for navigation, control, and communication during launch.
By Type: The radiation hardened segment dominated the market with a 55.69% share in 2026 and is estimated to be the fastest-growing segment, driven by rising demand for semiconductors that withstand space radiation environments. These components are hardened to resist damage from ionizing radiation, ensuring reliability and longevity in space missions. The radiation tolerant segment is expected to grow significantly due to increasing demand for low-cost, precise semiconductors — designed to endure certain radiation levels without complete hardening, offering a balance between performance and cost-effectiveness for missions with lower radiation exposure.
By Component: The integrated circuit segment dominates with a 28.85% share in 2026, estimated to grow significantly due to growing demand for multi-functional semiconductors. ICs consist of numerous electronic components — including transistors, resistors, and capacitors — fabricated on a single semiconductor substrate, playing pivotal roles in space applications including data processing, amplification, and control within compact, efficient packages.
Regional Outlook
North America held 44.06% of the global market in 2025, reaching USD 0.64 billion, projected to grow to USD 0.43 billion in 2026 — attributed to the presence of major OEMs and operators. In August 2022, Microchip Technology secured a major agreement with the U.S. government through the CHIPS and Science Act, aiming to strengthen the domestic chip industry against Chinese competition, with the U.S. Department of Commerce disclosing plans to allocate approximately USD 162 million to a specific company. The U.S. market is projected to reach USD 0.39 billion by 2026.
Europe reached USD 0.27 billion in 2025 (19.05% of total market revenue), projected to reach USD 0.18 billion in 2026 — the second-largest market in the base year, driven by growing space-based semiconductor applications and increasing investments. In February 2023, Infineon Technologies AG began construction of a new factory for analog/mixed-signal technology and power semiconductors in Dresden, with Germany's Federal Ministry for Economic Affairs and Climate Protection agreeing to an early project start ahead of European Commission financial review completion. The U.K. market is projected to reach USD 0.07 billion by 2026, while Germany is projected at USD 0.01 billion.
Asia Pacific contributed approximately USD 0.38 billion to the global market in 2025 (26.45% share), expected to reach USD 0.26 billion in 2026, and is expected to be the fastest-growing region — driven by strong economic development in emerging countries. In 2022, executives from AMD, Micron Technology, Applied Materials, and Foxconn pledged investment in India's semiconductor ecosystem, with AMD announcing a USD 400 million investment over five years including the world's largest R&D campus (500,000 square meters) in Bangalore, while Micron began building India's first semiconductor factory in Gujarat. Japan is projected to reach USD 0.02 billion by 2026, China at USD 0.15 billion, and India at USD 0.05 billion.
Rest of the World — including the Middle East & Africa and Latin America — accounted for USD 0.14 billion in 2025 (9.90% of global industry), expected to reach USD 0.1 billion in 2026, driven by increasing government initiatives for space-based technologies.
Connect with Our Expert for any Queries: https://www.fortunebusinessinsights.com/enquiry/speak-to-analyst/105223
Competitive Landscape
The market is consolidated with key players including Advanced Micro Devices, Inc. (U.S.), Infineon Technologies AG (Germany), Microchip Technology Incorporated (U.S.), Texas Instruments Incorporated (U.S.), STMicroelectronics N.V. (Switzerland), Renesas Electronics Corporation (Japan), Cobham Limited (U.K.), Solitron Devices, Inc. (U.S.), BAE Systems Plc (U.K.), and Teledyne Technologies Incorporated (U.S.). Companies focus on technological advancements, product innovations, and expansion into emerging markets to increase market share. In April 2022, Infineon Technologies unveiled the pioneering radiation-hardened Ferroelectric RAM (F-RAM) with a serial interface designed for space industry extreme environments, offering unparalleled reliability and data retention surpassing non-volatile EEPROM and serial NOR Flash devices in energy efficiency.
Key recent developments include SEEQC's March 2023 development of a digital chip designed to function at temperatures colder than outer space, compatible with quantum processors housed in cryogenic chambers; Lux Semiconductors' February 2023 securing of USD 2.3 million to advance its "System-on-Foil" process for enhanced microelectronics performance in spacecraft and aircraft applications; Texas Instruments' November 2022 expansion of its space-grade analog semiconductor range with a novel Space High-Grade (SHP) plastic packaging specification for radiation-hardened products; Microchip Technology's August 2022 securing of a USD 50 million federal contract from NASA's Jet Propulsion Laboratory to design a next-generation high-performance spaceflight computing (HPSC) system offering 100x more powerful computing capabilities than current systems; and STMicroelectronics' March 2022 launch of radiation-hardened power, analog, and logic ICs in low-cost plastic packages for satellite electronic circuitry, including data converters, voltage regulators, LVDS transceivers, and logic gates.
Curious About Japan’s Market? Explore the Latest - Space Semiconductor Market Insights