Software-Defined Radio Market Overview Analysis By Fortune Business Insights Analysis
Market Size & Growth Outlook
According to Fortune Business Insights: The global software-defined military radio market was valued at USD 4.76 billion in 2025 and is projected to grow from USD 5.34 billion in 2026 to USD 10.88 billion by 2034, exhibiting a CAGR of 9.3% during the forecast period.
The market represents a critical evolution in defense communications, enabling flexible, adaptable platforms that replace rigid hardware-defined systems with software-configurable waveforms. This shift supports network-centric warfare by allowing seamless interoperability across land, air, naval, and space domains, even in contested electromagnetic environments jammed by adversaries. Driven by global military modernization efforts, the market emphasizes cognitive radios that dynamically optimize spectrum usage, integrate with emerging 5G networks, and incorporate AI for enhanced signal processing and security.
Key players, including BAE Systems, Northrop Grumman, Raytheon Technologies/RTX, Elbit Systems, Thales, L3Harris, General Dynamics, Viasat, Leonardo, and Rohde & Schwarz, dominate the market through secure tactical communications portfolios and large-scale defense program wins, with long-term upgrade and support models turning radio procurement into a multi-year modernization cycle across land, air, and naval forces.
Get a Sample Research PDF: https://www.fortunebusinessinsights.com/enquiry/request-sample-pdf/102524
Market Trends
Rising Adoption of Adaptable SDR Platforms: The market is experiencing robust growth, driven by defense modernization and integration with 5G infrastructure. Key trends include the shift to cognitive radios for spectrum optimization, reduced size, weight, and power via semiconductor advances, and the global adoption of SDR technology in most tactical military radios. This evolution supports network-centric warfare, extends equipment lifecycles, and enhances interoperability in contested environments.
Market Drivers
Defense Modernization and Budget Increases: Surging global defense budgets prioritize SDR for tactical advantages, including flexible frequency reconfiguration, secure data transfer, and seamless interoperability across platforms. Military programs such as the U.S. Joint Tactical Radio System and rising geopolitical tensions drive adoption, with over 40,000 units delivered to Ukraine by L3Harris Technologies, Inc. in 2025 for jamming-resistant updates. Integration with 5G, AI signal processing, and network-centric operations further drives demand by improving voice clarity, bandwidth, and lifecycle cost savings compared with legacy hardware.
Market Restraints
High Costs and Implementation Complexity: Elevated initial investments and FPGA expenses limit broader adoption, particularly for new entrants facing steep development hurdles. Cybersecurity vulnerabilities, export controls, and thermal management issues constrain scalability, while reliance on specialized expertise slows deployment. High system complexity requires rigorous certification to military standards, which extends timelines and increases operational expenses, and maintenance difficulties for subsystems hinder sustained use in diverse environments.
Market Opportunities
AI-Enabled Cognitive Radios and Exports: Significant opportunities arise from AI-integrated adaptive architectures for real-time spectrum management in contested electromagnetic spaces, alongside expansion into space-based SDR and unmanned systems integration. Defense exports, international collaborations, and commercial 5G crossovers, such as cloud-bundled industrial-edge stacks, enable rapid network launches and lower barriers to entry via Open RAN. Emerging markets in Asia Pacific, fueled by rising military spending in China and India, as well as modernization in Europe and North America, further amplify growth potential through government-backed programs.
Market Challenges
Interoperability and Security Barriers: Integrating SDR with legacy systems poses major hurdles due to mismatches in protocols, modulation schemes, and technical specifications, which complicate upgrades across mixed fleets. Stringent security requirements vary by nation, restricting waveforms and market access, while certification for electromagnetic compatibility and cyber threats prolongs qualification. Evolving threats such as electronic warfare jamming demand constant software updates, straining resources amid geopolitical export limits and supply chain dependencies.
Segmentation Analysis
By Component: Hardware is anticipated to account for the largest market share, as forces still need large volumes of radios for soldiers and vehicles, with replacement cycles, ruggedization needs, and secure, standardized terminals driving procurement. Software is anticipated to grow at a CAGR of 9.7% over the forecast period.
By Type: General purpose radio dominated the global market in 2025, since demand is steady as it covers everyday tactical voice and data needs across units, and buyers prefer proven models with simpler integration, strong availability, and upgrade paths. Cognitive/intelligent radio is projected to grow at a CAGR of 10.4% over the forecast period. The market also covers the Joint Tactical Radio System (JTRS) and Terrestrial Trunked Radio (Tetra).
By Frequency Band: UHF is anticipated to hold the dominant market share over the forecast period, as it offers a balance of range, penetration, and reliable tactical performance in complex terrain, supporting air-ground coordination and mobile units. The other bands segment is projected to grow at a CAGR of 10.3% over the forecast period. MF/HF and VHF round out the segmentation.
By Platform: Land dominated with the largest market share, as armies deploy the most radios across infantry, vehicles, and command posts, and modernization programs prioritize secure networking, wide fielding, and consistent upgrades for frontline readiness. Space is projected to grow at a CAGR of 10.6% during the forecast period, alongside airborne and naval platforms.
Regional Outlook
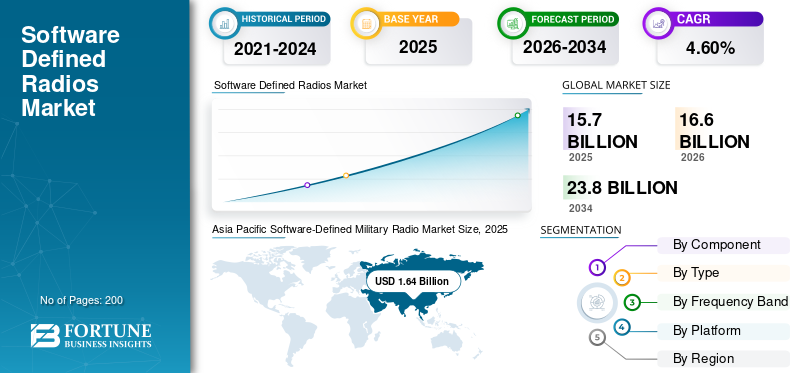
The report credits Asia Pacific with a 34.45% market share in 2025 in its key takeaways, while the detailed regional breakdown reports the region at USD 3.0 billion (20.90% share) in 2025, rising to USD 4.0 billion in 2026. Regional demand is driven by border tensions, maritime security, and force expansion, with buyers seeking affordable, scalable SDRs, domestic production, and rapid fielding, especially for army modernization and joint operations. Japan's market is estimated at around USD 0.31 billion in 2026, driven by island defense and Self-Defense Force coordination needs. China's market is projected at around USD 0.66 billion in 2026, driven by force modernization and networked radios for land and maritime theaters. India's market is estimated at around USD 0.34 billion in 2026, as services replace legacy systems and prioritize locally produced SDRs.
North America held 32.90% of the global market in 2025, reaching USD 5.2 billion, and is projected to grow to USD 5.5 billion in 2026, as the U.S. refreshes tactical networks and allies align on interoperability. The U.S. market is estimated at around USD 1.44 billion in 2026, about 9.2% of global sales, led by large-scale tactical networking programs and continuous upgrades.
Europe reached USD 4.7 billion in 2025, representing 30.10% of total market revenue, and is projected to reach USD 5 billion in 2026, as nations modernize coalition communications and build sovereign industrial capacity. The U.K. market is estimated at around USD 0.30 billion in 2026, and Germany's market is projected at approximately USD 0.33 billion.
Rest of the World, covering the Middle East & Africa and Latin America, accounted for USD 2.6 billion in 2025 (16.20% share) and is expected to reach USD 2.7 billion in 2026. The Middle East & Africa and Latin America are set to reach USD 0.19 billion and USD 0.10 billion, respectively, in 2026, with demand uneven but rising, particularly where internal security and regional conflicts persist, and investment prioritizing rugged radios, secure voice/data, and training packages.
Competitive Landscape
Key players are driving the market by helping armies and air forces replace older radios with modern, software-upgradable systems. Major U.S. players such as Northrop Grumman, Raytheon, L3Harris, General Dynamics, Viasat, and BAE Systems win large programs, deliver radios at scale, and keep them relevant through upgrades and long-term support. European leaders such as Thales and Leonardo grow the market through cross-country interoperability, national manufacturing partnerships, and service contracts that keep fleets running for years. Elbit Systems expands its share through proven tactical radios designed for fast deployment and harsh battlefield conditions. Rohde & Schwarz supports wider adoption by improving testing, reliability, and secure performance standards.
Companies profiled include BAE Systems PLC (U.K.), Northrop Grumman Corporation (U.S.), Raytheon Technologies Corporation (U.S.), Elbit Systems Ltd. (Israel), Thales Group S.A. (France), L3Harris Technologies, Inc. (U.S.), General Dynamics Corporation (U.S.), Viasat, Inc. (U.S.), Leonardo S.p.A. (Italy), and Rohde & Schwarz GmbH & Co. KG (Germany).
Connect with Our Expert for any Queries: https://www.fortunebusinessinsights.com/enquiry/speak-to-analyst/102524
Key Industry Developments
October 2025: The Indian Army placed an order for its first homegrown software-defined radios, based on a DRDO design and to be manufactured by Bharat Electronics Limited.
July 2025: Indra and Bittium signed a non-binding agreement outlining cooperation on SDR development, exploring Bittium technology transfer while Indra adapts the solution to help build Spain's industrial capability for a Europe-based, fully proprietary SDR and waveform solution.
June 2024: Thales secured a major deal to equip Ireland's Army, Naval Service, and Air Corps with SDR systems and support, including an initial supply of more than 3,500 SquadNet radios and roughly 2,500 radios from the SYNAPS range under a framework agreement.
February 2024: The Indian Air Force signed a contract with Bharat Electronics Limited to procure lightweight, software-based, man-portable radio communication sets.
January 2023: Elbit Systems stated that Spain's DGAM selected its E-LynX tactical SDR solution for an urgent procurement program focused on V/UHF SDR radio equipment.
Explore Japan’s Market Opportunities - Latest Software Defined Radio Market Insights