Self-employment gives the person flexibility and freedom, but the application process for getting a mortgage becomes more complex compared to one who has a regular salary. Self-employed individuals, such as a business owner, freelancer, contractor, professional, or incorporated business owner, might not have consistent annual income, and therefore the lenders tend to focus more on the income earning process.
When looking for a Self-Employed Mortgage in British Columbia, knowing the requirements prior to the application process could go a long way in making the entire process easier for you.
What Are the Requirements for a Self-Employed Mortgage in British Columbia?
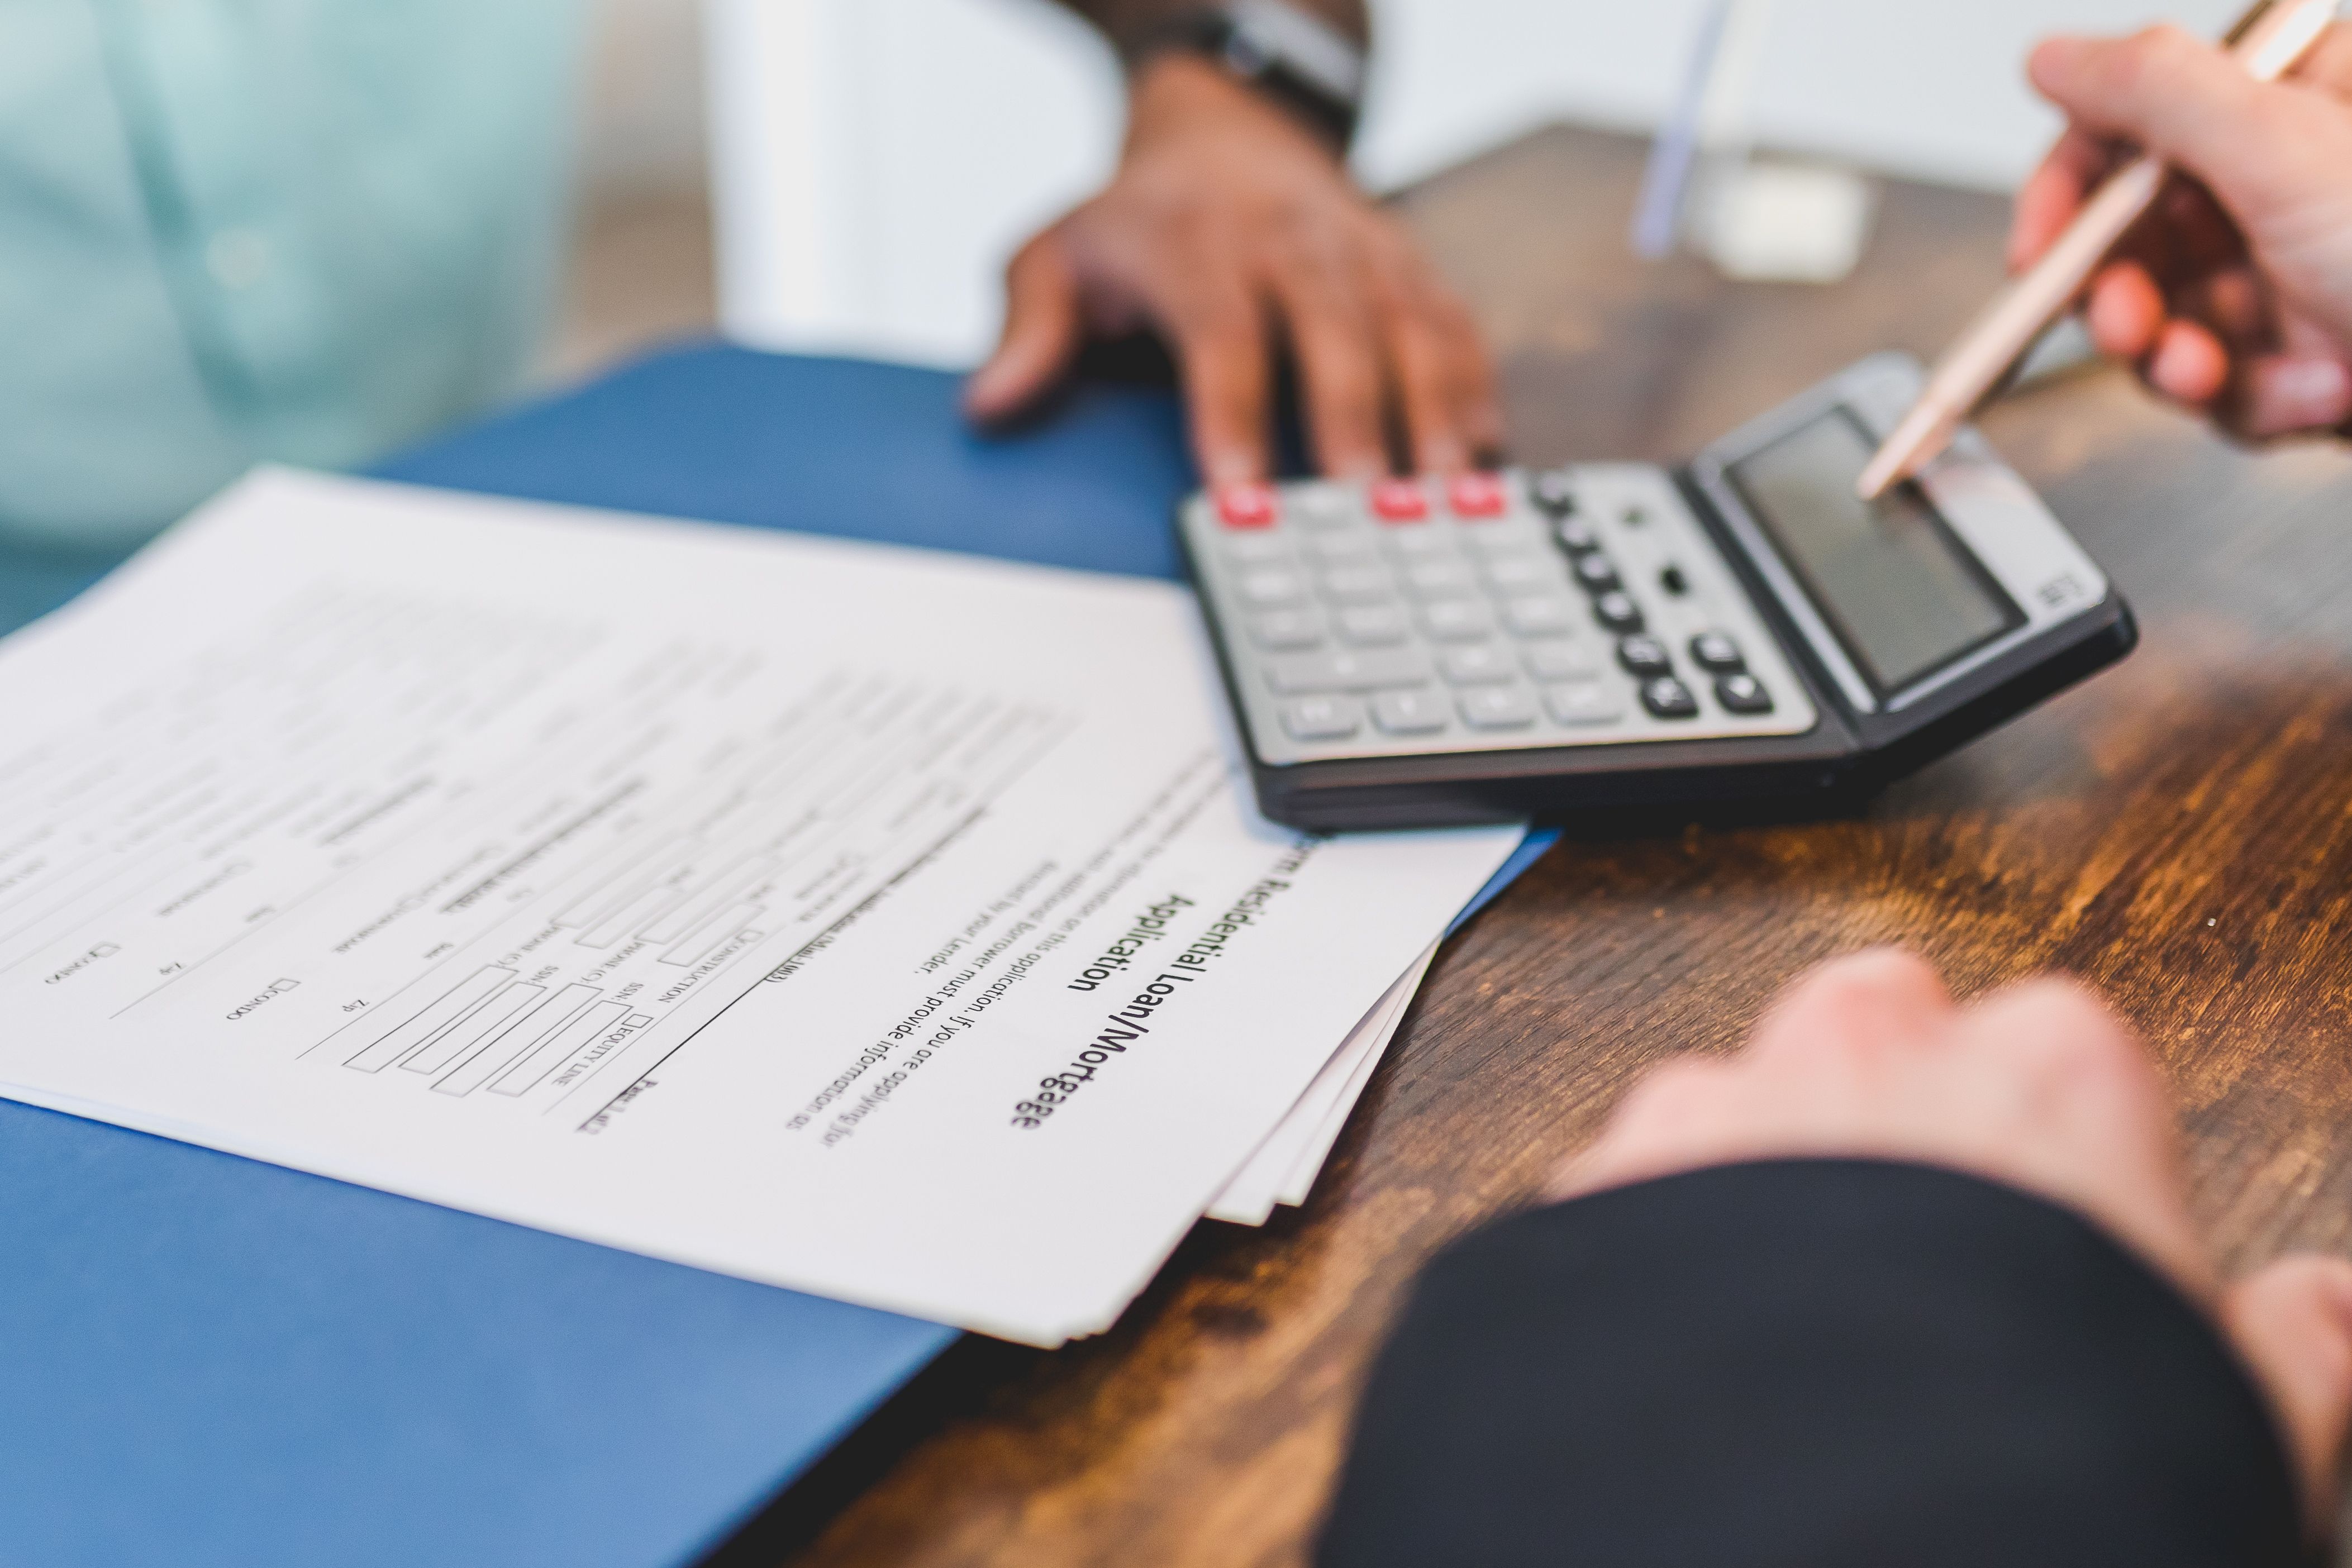
There isn't one set of requirements that applies to every self-employed borrower. Mortgage lenders have their own policies for assessing income, business history, credit, debt, and the property being purchased.
Generally, you may be asked to provide documents such as:
- Personal Notices of Assessment (NOAs)
- T1 General tax returns
- Business financial statements
- Proof of business registration
- Business bank statements
- GST returns, where applicable
- Contracts or invoices showing ongoing business activity
- Proof of your down payment
- Information about existing debts and financial obligations
The Canada Mortgage and Housing Corporation (CMHC) notes that self-employed borrowers may use different forms of documentation depending on their circumstances, including tax returns, business documents, financial statements, contracts, and business account statements.
Getting a Mortgage If Self Employed
One of the first and most important steps of getting a mortgage if you are self employed is to organize your finances prior to the application process.
Begin by looking at your past tax returns and business finances. Ensure that your income has been accurately reported and that you can provide explanations for any major variations each year. You should always try to organize both your personal and business finances to allow easy access to lenders and/or mortgage professionals.
Your credit score plays an important role as well. Begin by looking at any outstanding debts, credit card debts, loans, and all other monthly payments prior to applying for a mortgage. Lenders take into consideration income, assets, debt, and where the down payment funds originate from.
Pre-approval will help you determine your financing potential prior to searching for a home.
How Are Self-Employed Income Calculations Performed By Lenders?
One common query raised by entrepreneurs is how to determine self-employed income for mortgage calculations.
This calculation depends on the structure of the business, income history, and the lender's requirements. The income earned by an entrepreneur may be relatively low due to legitimate business deductions in the tax return. However, some mortgage products will enable some eligible business deductions to be added back or adjusted while calculating qualifying income.
For instance, in CMHC's Self-Employed mortgage product, some eligible business deductions may be considered using either the add-back or the gross-up method depending on qualifying circumstances.
This explains why the income on tax returns is not always reflective of the actual income when mortgage approval is being sought.
In case of sole proprietorship or partnership business structures, CRA requires that business income and deductions should be reported on the relevant tax slips. This means that maintaining proper financial records is not just for tax purposes but also to prepare for mortgage financing.
Duration of Self-Employment?
The historical background of self-employment is yet another factor considered by some lenders. It would help prove stable income sources.
CMHC says that at least 24 months of business experience or being engaged in the same activity is preferred for its self-employed mortgage insurance plan, even though alternative solutions may exist for recently self-employed individuals who satisfy other requirements.
Recently started working for yourself? This does not necessarily mean that you cannot buy a house. The previous experience, prospects of your business, contracts, savings, and other financial factors might matter in your case as well.
Is It Important How Much You Pay as a Down Payment?
Yes, because your down payment is a key aspect of any mortgage application, including a mortgage for self employed people.
The amount of money needed for a down payment depends on various factors, such as the cost of the property, the type of the mortgage, and the lender's rules. In case you do not have 20% down, you will need to pay mortgage loan insurance, provided that your mortgage falls under the relevant insurance requirements. Besides, according to the Financial Consumer Agency of Canada, a lender may ask you to pay more as a down payment, if you are a self-employed person.
A well-documented source of funds is no less important than the amount of the down payment.
Credit and Debts Still Count
Just because you are a self-employed individual does not mean that lenders will disregard your credit rating and outstanding debts when figuring out what you can afford.
A good credit score, a low debt level, reliable business income, and proper paperwork can all be helpful in creating a stronger application.
The fact that one lender cannot accommodate the needs of the applicant doesn't mean that other lenders won't be able to do the same. In some cases, talking to a mortgage expert can prove helpful in such situations.
Preparing for Your Mortgage Application
Before applying for a Self-Employed Mortgage in British Columbia, consider preparing the following:
- Review your recent tax returns and Notices of Assessment.
- Organize personal and business bank statements.
- Gather business registration and financial documents.
- Check your credit report and outstanding debts.
- Prepare evidence showing the stability of your business income.
- Confirm where your down payment and closing funds will come from.
- Discuss your situation with a mortgage professional before making an offer.
Being prepared can reduce delays and help ensure the lender receives the information needed to assess your application.
Mortgage Choices Suited for You
Being self-employed does not mean that you cannot apply for home financing. It all boils down to how lenders consider business income and the kind of paperwork you can provide.
For those who are searching for information about Self employed mortgage in British Columbia requirements, we at Sunlite Mortgage are here to provide you with solutions to mortgage loans according to your situation. Be it freelance, construction, or incorporation, being aware of what options you have before applying is beneficial.